AP Inter 1st Year Economics 10th Lesson Money, Banking and Inflation Questions and Answers
Essay Questions
Write an essay on the following questions.
Question 1.
Write the functions of commercial banks.
Answer:
Commercial banks play a very important role in economic growth of a country. It is a financial institution. It is a profit making business firm dealing with money. Modern banks in India are joint stock companies registered under the Indian Companies Act.
Definitions of Bank:
- According to Sayers “we can define bank as an institution whose debts are widely accepted in settlement of other people’s debts. ”
- According to Crowther “a bank collects money from those who have it to spare or who are saving it out of their incomes, and lends this money to those who require it. ”
Functions of Commercial Banks :
Functions of Commercial Banks have been classified into various types as mentioned below.
- Primary functions
- Secondary functions
- Creation of credit
- Agency functions
- General utility services
1. Acceptance of Deposits : One of the primary functions of a commercial bank is to accept deposits from the public. The deposits accepted by the banks are of the following types.
a) Savings deposits : These deposits are made into a savings account of a bank. These deposits encourage savings habit among the public. These are most convenient to small businessmen, salaried employees, artisans, etc. The rate of interest paid on these deposits is comparatively low and it is around 4% per annum.
b) Current deposits: These are the deposits made into the current account of a bank. These are most convenient to the business people, public authorities, and joint stock companies, because there are no restrictions on the number and the amount of withdrawals. Bank do not pay any interest on these deposits.
c) Term deposits : These are also called fixed deposits because the money is deposited with the bank for a fixed period of time. These deposits can be withdrawn after the expiry of maturity period. These deposits carry more interest than the saving deposits. The rate of interest varies from 6% to 12% per annum depending on the period of deposits.
d) Recurring or Cumulative deposits : These are the variants of fixed deposits. These deposits are very convenient to those who can’t save huge amount at a time. These are the monthly installments for a fixed period of time. A fixed amount in the multiples of Rs. 10 may be deposited every month for a period one or more years. These deposits carry rate of interest at a rate more than that of savings bank and less than that of a term deposit.
2. Payment of Loans and Advances: Another primary function of the commercial bank is to give loans and advances to different sections of the public like traders, industrialists, farmers, artisans, etc.
a) Demand loans / Call loans : A demand loan is a loan that should be repaid on demand by the bank. The entire loan amount is credited to the account of the borrower in a lump sum. The entire amount carries rate of interest from the date of credit. This loan is a kind of advance made with or without security. These are also called call loans.
b) Short term loans : These loans are given for a specified short period. They are sanctioned to businessmen and farmers, etc. to finance working capital. Individuals may also receive such loans as personal loans. They are given against security.
c) Cash credits : Banks give cash credit to business firms and industries against current assets such as shares, stocks, bonds, etc. up to a specified limit. The customer need not withdraw the entire amount in one installment. He may withdraw as and when he needs and interest is charged on the amount of actual withdrawal.
d) Overdraft. This is a facility allowed by the bank to current account holders. Sometimes they are allowed to withdraw amount above the balances in their account up to a limit. Interest is charged on the amount of actual withdrawal.
e) Discounting of bills of exchange: The most useful and popular form of bonding is by discounting “bills of exchange”. These are undertakings
written by the buyers and given to sellers when the transaction is made on credit basis. The buyer undertakes to make payment after a specified period or on a specified future date.
f) Credit cards : Now-a-days banks devised new methods of giving loans to the customers. One such popular method is issuance of the credit card. A credit cardholder can use his card to purchase goods on credit from specified firms and shops subject to certain regulations. The card holder pays the amount to the bank on a later date with interest.
3. Creation of Credit: The unique function of commercial banks is creation of credit. This type of credit is created from out of the primary deposits of money received from the public. Part of the total amount of these deposits is given as loans and advances to its customers.
4. Agency Functions: Along with above functions commercial banks perform certain agency functions also. Some of the important agency functions are;
- Collection of cheques, drafts, bills of exchange, etc. of their customers from other banks.
- Collection of dividends and interest from business and industrial firms.
- Purchase and sale of securities, shares, debentures, government securities on behalf of the customers.
- Acting as trustees and keeping their funds in safe custody.
- Making payments such as insurance premium, income tax, etc. on behalf of their customers as per their advice.
5. General Utility Functions: Besides the above agency functions, commercial banks provide certain utility services to their customers.
- They provide locker facility for the safe custody of the silver, gold ornaments, etc.
- They transfer money of the customers from one bank to the other by way of demand drafts, mail transfer, etc. by collecting commission from them.
- With the use of computers and internet facility, now-a-days the banks are facilitating online transfer of money from one bank to the other.
- They issue letters of credit to help the traders and businessmen.
- Traveller’s cheques are issued by the commercial banks to avoid the risk of carrying of cash.
- They provide foreign exchange to the customers for exports and imports in connection with their business.
- They convey information on behalf of their customers to the businessmen operating in other places.
- Recently the commercial banks have been establishing ATMs at different locations to enable their customers to withdraw cash from their accounts.
Question 2.
State the functions of the RBI.
Answer:
Reserve Bank of India is the Central bank of India. It was established in April 1935 with a share capital of Rs. 5 crores. It was originally owned by private shareholders but it was nationalized in 1949. It performs all the Central bank functions under RBI Act, 1934.
Functions of RBI : RBI performs the following functions.
1. Note Issue : RBI has the monopoly of note issue in the country. It maintains gold and foreign exchange reserves of a minimum Rs. 200 crores of which gold should be worth of 115 cores. RBI issues currency notes of the denomination of Rs. 2000,1000, Rs. 500, Rs. 100, Rs. 50, Rs. 20, and Rs. 5, Rs. 2, one rupee note and other coins are issued by the Finance Ministry of the Government of India but circulated by the RBI.
2. Banker of Government: RBI acts as the banker, agent and advisor to the Government of India. It is the agent of the Government of India and all the State governments except the Government of Jammu and Kashmir. It receives money and makes payments on behalf of the Government and keeps the cash balances as deposits without any interest.
3. Bankers’ Bank : RBI serves as a Banker not only to the Government but also to the banks.
- All the scheduled banks are bound by the state to maintain with RBI a part of their total deposit amount as cash balances. This ratio is called the Cash Reserve Ratio (CRR).
- RBI provides financial assistance to the commercial banks in times of their financial stringency or crisis / problems by giving loans or rediscounting the bills of exchange.
- It acts as a clearing house for settlement of inter-bank accounts.
4. Lender of last resort: In times of financial crisis the schedule banks can approach the RBI as a last resort. The RBI grants them loans against the securities such as treasury bonds, treasury bills and other approved securities. The RBI may also provide financial assistance by rediscounting the eligible bills of exchange.
5. Clearing House : Businessmen and other customers issue cheques towards payment for their transactions. A businessman or customer may get a cheque issued on a bank in which he has no account. He has to deposit it in his bank and which collects the amount from the bank on which the cheque is issued.
6. Custodian of foreign exchange reserves : The RBI acts as a custodian of foreign exchange reserves for the country. It has also the responsibility of maintaining the stability of foreign exchange rate. As a member of the International Monetary Fund, it maintains the stability of the exchange rate between the Indian currency and currencies of the member countries.
7. Credit controller: It is the responsibility of RBI to control the volume of credit in the country. It controls credit through different quantitative and qualitative control methods. RBI announces a credit policy for every six months suitable to the credit needs of the country.
8. Supervisory functions : The RBI, being the apex institution of the banking system, exercises wide powers of supervision and control over all the commercial banks and the cooperative banks through the system of licensing, inspection and amalgamation of banks.
9. Promotional and developmental functions : It performs certain promotional and developmental functions also in order to achieve economic development.
- Takes steps for establishment of banks throughout the country and expansion of their branches.
- Refinances the state cooperative banks and the financial institutions which give agriculture credit.
- Promotes different financial institutions to provide industrial finance.
Question 3.
Explain how inflation affects production, income and distribution.
Answer:
Effects of inflation : The effects of Inflation on production and distribution can be explained below.
1. On production:
- Mild inflation stimulates production, as it increases the profit margin of entrepreneurs.
- High inflation rate or hyperinflation hinders production.
- Inflation discourages savings. This affects the capital formation, which in turn affects production.
2. Income and Distribution : The impact of inflation is not uniform on all sections of people. It affects certain sections of the people adversely, while certain other sections may benefit from inflation. This can be elaborated as follows:
- Fixed income groups : People belonging to fixed income groups suffer due to inflation because, their incomes remain constant even prices of commodities rise.
- Working class : Workers and wage earners in the informal sector normally work for incomes. Even otherwise their wages do not rise when prices rise. Such people suffer because of inflation.
- Debtors and creditors : Inflation results in a decline in the value of money. Therefore, creditors lose as‘the value of money is higher when they have lent and less when they are repaid. But debtor gains because the value of money is high when they borrowed but low when they repay.
- Consumers and entrepreneurs : Inflation can negatively impact the consumers. During inflation, the purchasing power of money will be less, hence, consumer will suffer during inflation. On the other hand, entrepreneurs gain from inflation by selling more output at higher prices.
Question 4.
Examine the difficulties of the barter system.
Answer:
Prior to the introduction of money, people can exchange one commodity for another commodity. This method of exchanging good is called “barter system”. This system consists of several difficulties. These are as follows :
- Lack of coincidence of wants : Under the barter system, the buyer must be willing to accept the commodity which the seller is willing to offer in exchange. The wants of both buyer and seller must coincide. This is called coincidence of wants.
E.g: Suppose the seller has a goat and he is willing to exchange it for rice. Then the buyer must have rice and he must be willing to exchange rice for goat. - Lack of store value: Some commodities are perishable. They perish within a short time. It was not possible to store the value of such goods in their original form under barter system.
- Lack of divisibility of commodities : Exchange of goods or commodities was possible when we divide the goods into small units. But in reality all commodities are not divisible. This is particularly true in the case of animals.
- Lack of common measure of value : Under the barter system, there was no common measure of value. To make exchange is possible, it was necessary to determine the value of every commodity in terms of every other commodity.
- Difficulty in making deferred payments: Deferred payments means, payments to be paid in future for present transaction. But it is not possible in barter system. Because future exchange involved some difficulties.
E.g: Suppose it was agreed to sell specific quantity of rice in exchange for a goat on a future date keeping in view that present value of the goat. But the value of goat may decrease or increase by that date.
Question 5.
Explain the functions of Money.
Answer:
The term “Money” was derived from the name of Goddess Juno Moneta of Rome. Prior to the introduction of money, the barter system was introduced. To eliminate difficulties in barter system, money was introduced. Money plays a key role in < Modern Economics. A modern economy is rightly known as Monetary Economy.
Definitions of Money : Several economists have defined money in several ways. Some are given below:
- According to Seligman, “Money is one that possesses general acceptability”.
- According to Walker “Money is what money does”.
Functions of Money : The functions of money may be classified into 4 types.
- Primary functions,
- Secondary functions,
- Contingent functions,
- Static and dynamic functions
1) Primary functions The primary functions of money are really the technical and important functions of money. They are of two types,
a) Medium of exchange : The most important function of money is to serve as a medium of exchange. It removes the inconveniences of the barter system in which exchange of goods was possible If only there was double coincidence of wants.
Money serves as a medium of exchange and facilitates the buying and selling of goods. People can exchange goods and services through the medium of exchange.
b) Measure of value: Money serves as a measure of the value of goods and services. The value of goods and services is expressed in terms of money. It has removed the difficulty of the barter system and has made transactions simple and easy. The value of each commodity is expressed in the units of money. We call it the price.
2) Secondary functions : The secondary functions of money has been classified into “3 types”.
a) Store of value : The value of goods and services can be stored in the form of money. Certain commodities are perishable. If they are exchanged for money before they perish, their value can be preserved in the form of money.
b) Standard of deferred payments : Money serves as a standard of deferred payments. In modem economics, most of the business transactions take place on in the form of credit. An individual consumer may now purchase a commodity and pay for it in future because it is possible to express future payments in terms of money.
c) Transfer of money: Money can be easily transferred from one person to another at any time and at any place.
3) Contingent functions Besides the primary and secondary functions, money has certain contingent functions also. These are classified into 4 types.
a) Measurement and distribution of national income: National income of a country can be measured in terms of money by aggregating the value of all commodities. It is not possible in a barter system. In the same manner, national income can be distributed to different factors of production like (N, L, K, O) by making payments to them (rent, wage, interest, profit) in money terms.
b) Money equalizes marginal utilities: The consumer can measure utilities of goods in money terms and he can equalize the marginal utilities of different commodities which are purchased by them with the help of money.
c) Basic for credit: Credit is created by banks from out of primary deposits of money. It is the basis of modem economic progress. The supply of credit in an economy depends on the supply of nominal money.
d) Liquidity: Money is the most important liquid asset. All types of properties can be converted into money easily. Money is 100% liquid.
4) Static and dynamic functions of money “Paul Engig” classified the functions of money as static and dynamic functions.
a) Static functions: The functions like medium of exchange, measure of value, store of value and deferred payment are the traditional functions or technical functions of money. In the point of Engig all these are called static functions of money. These functions do not show any effect on the economic development.
b) Dynamic functions: The functions of money which influence output, consumption, distribution, and general price level are called dynamic functions of money. The contingent functions come under dynamic functions.
Question 6.
Write note on supply of money.
Answer:
Money supply includes all money in the economy. It is a stock concept. There may be increase or decrease in the money stock over a period of time. The components of money supply may vary from country to country. Money supply consists of the following:
- Currency issued by the Central Bank In any country the Central Bank issues currency. It consists of paper notes, and coins. In India RBI, which is the Central Bank of the country, issues notes in the denominations of 500,100, 50, 20,10, 5 and 2 rupees. The one rupee note and coins are issued by the Finance Ministry of the Government of India.
- Demand deposits created by Commercial Banks : Bank deposits are a prominent component of money supply. Commercial banks create credit from the primary deposits of money received from the public. Credit is created in the form of deposits called derived or secondary deposits. In developed countries, they constitute nearly 80% of money supply.
Monetary aggregates : In India money supply is measured in terms of the following monetary aggregates.
M1 = Currency + demand deposits + other deposits
M2 = M1 + time liability portion of savings deposits with banks + certificates of deposits issued by banks + term deposits maturing within one year.
M3 = M2 + term deposits over one year maturity + call / term borrowing of banks.
Question 7.
Define Inflation. Explain the causes of inflation.
Answer:
Introduction: Inflation is one of the serious macro-economic problems confronting all the economies in the world today. It affects the economic lives and the welfare of the people in many ways.
Inflation: Inflation means a general rise in prices. It is a continuous rise in the general price level rather than once for all rise in it.
Definitions :
- According to Samuelson, “Inflation denotes a rise in the general level of prices”.
- According to Ackley, “Inflation is a persistent and appreciable rise in the general level or average of prices”.
Causes of Inflation : Inflation may occur due to the following reasons.
- Excess demand
- Supply shortage or increased cost of production
1. Factors causing increase in the aggregate demand for commodities :
a) High rate of population growth
b) Increase in non-plan and plan expenditure of government
c) Rise in government expenditure on employment and welfare schemes
d) Rise in the per capita income of the people due to economic development
e) Heavy investment on development projects with long gestation period
f) Increase in the money supply in the economy
g) Liberal availability of credit for unproductive economic activities
h) Deficit financing by the government
i) Reduction in direct tax rates.
2. Factors that raise the cost of production :
a) Increase in cost of factors of production
b) Rise in the prices of capital equipment
c) Increase in the tax rates
d) Excessive wear and tear of machinery
e) Import of machinery and equipment at higher prices
fj Devaluation of domestic currency
g) Inefficiency in management
h) Lack of optimum allocation of resources
3. Factors causing inadequate supply :
a) Failure of monsoons, floods, etc. in agriculture.
b) Shortage of investment
c) Non-availability of inputs and raw materials
d) Under-utilization of productive capacity
e) Long gestation period of certain industries
f) Exports at the cost of domestic supply
g) Artificial scarcity due to black-marketing.
Question 8.
Explain the payment system of Electronic (or) Online banking.
Answer:
Mobile Banking All banking transactions can be performed using a smartphone through a mobile ‘app’ of the respective banks. This is very popular now.
Payment Systems
a) Real Time Gross Settlement (RTGS) : The RTGS system is a fund transfer mechanism where the transfer of money takes place from one bank to another on a ‘real time’ and on ‘gross basis’. This is the fastest possible money transfer system through the banking channel. Settlement in real time means payment transaction is not subjected to any waiting period. The transactions are settled as soon as they are processed. In India, the Reserve Bank of India maintains this payment network. There is no limit on the amount to be transferred.
b) National Electronic Fund Transfer (NEFT) ;The NEFT system is a nationwide system that facilitates individuals, firms and corporates to electronically transfer funds from any bank branch to any individual, firm or corporate having an account with any other bank branch in the country. There is a limit of Rs. 2 lakhs. Transfer is done in batches and hence there is waiting time. NEFT requires an IFSC to perform transactions.
Only domestic transactions are possible through RTGS and NEFT. For international transactions, there is another system called SWIFT (Society for Worldwide Interbank Financial Telecommunication).
c) Immediate payment Services (IMPS) :The IMPS is a 24/7 interbank electronic fund transfer system in India that enables instant money transfers via mobile, internet and ATM channels.
d) Unified Payments Interface (UPI): UPI is a payment system that enables transactions through mobile apps. Eg.: Phonepe, G-Pay, Paytm etc. National Payments Corporation of India (NPCI) established in 2008, promoting and manages UPI.
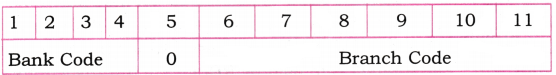
e) Indian Financial System Code (IFSC) : Core Banking enabled banks and branches are assigned an Indian Financial System Code (IFSC) for RTGS and NEFT transactions. IFSC is an 11 digit alphanumeric code and unique to each branch of a bank.
The first ‘4’ alphabetic characters representing the bank name, and the last ‘6’ characters (usually numeric) representing the branch. The 5th character is 0 (zero) and reserved for future use.
Question 9.
Explain the policy tools of Control Money Supply or Monetary Policy.
Answer:
Policy tools to control Money Supply (Monetary Policy) : Monetary policy is the policy adopted by the monetary authority of the nation (i.e., RBI). The main objectives of monetary policy in India are:
- Price stability,
- Exchange Rate stability,
- Employment generation, and
- Control of money supply, etc.
The RBI controls the money supply in the economy in various ways. The tools used by the central bank to control money supply can be quantitative or qualitative.
Quantitative (or) General Measures:
a) Bank Rate : The Bank Rate is the rate at which the Central Bank discounts the bills of commercial banks. It is also known as discount rate. If the Central Bank wishes to control credit and inflation in the economy, it raises the Bank Rate. If the Central Bank wishes to boost production and investment activities in the economy, it will decrease the Bank Rate.
b) Open Market Operations : It implies the deliberate direct sales and purchases of securities and bills in the market by the Central Bank on its own initiative to control the volume of credit. If RBI wants to discourage credit in the economy, it sell its securities. This step leads to contraction of credit and money in circulation.
If RBI wants to encourage credit in the economy, it purchases its securities. This measure leads to expansion of credit and money in circulation.
c) Cash Reserve Ratio (CRR): CRR refers to that portion of total deposits which a commercial bank has to keep with the Central Bank in the form of cash reserves. Cash reserves determine the capacity of the commercial banks to create credit. During inflation the CRR is raised consequently, credit contracts. During deflation or recession, CRR is reduced. This will facilitate credit expansion.
d) Statutory Liquidity Ratio (SLR) : SLR refers to that portion of total deposits which a commercial bank has to keep with itself in the form of liquid assets like cash, gold or approved government securities. Liquidity impacts the credit creating ability of commercial banks.
If RBI wants to discourage credit in the economy, it increases SLR and if it wants to encourage credit in the economy, it decreases SLR.
e) Repo Rate : Repurchase options or in short ‘Repo’is defined as ‘an instrument for borrowing funds by selling securities with an agreement to repurchase the securities on a mutually agreed future date at agreed price, which includes interest for the funds borrowed’. The interest rate charged by RBI for this transaction is called the ‘repo rate’. Changes in repo rate influence the quantity of credit in the economy.
f) Reverse Repo Rate : ‘Reverse Repo’ is defined as “an instrument for lending funds by purchasing securities with an agreement to resell the securities on a mutually agreed future date at an agreed price which includes interest for the funds lent”. The interest rate paid by RBI for such transactions is called the reverse repo rate. Changes in reverse repo rate lead to expansion or contraction of credit.
Qualitative measures :
These are also known as selective credit controls. They include changing margin requirements, changing credit regulatory conditions, issuing directives, rationing of credit and moral suasion. RBI can also take direct action. These measures help in directing the credit to the desired sectors and purposes.
Question 10.
Write the methods of measuring inflation in India.
Answer:
Methods of Measuring Inflation in India : Whole sale Price Index (WPI) and Consumer Price Index (CPI) are two commonly used measures that later effective in determining the inflation in the country. WPI only consider changes in the price of goods. Whereas CPI considers changes in the prices of both goods and services.
a) Wholesale Price Index (WPI): It measures the changes in the prices of goods sold and traded in bulk by wholesale businesses to other businesses. WPI indices are published by the Office of “Economic Adviser, Ministry of Commerce and Industry”. It is the most widely used inflation indicator in India. The base year for the all India WPI has been revised from 2004-05 to 2011-12 in 2017. The WPI was calculated using about 435 elements in the base year 1993-94, but 697 items in the advanced foundation base year 2011-12.
b) Consumer Price Index (CPI): It measures price changes from the perspective of retail buyers (consumers). It is released by the “National Statistical Office (NSO)” of the Ministry of Statistics and Program Implementation (MoSPI). The CPI calculates the difference in the price of commodities and services such as food, medical care, education, electronics etc, which Indian consumers buy for final consumption.
There are 4 types of CPI indices. They are CPI for Industrial Workers (IW), CPI for Agricultural Labourer (AL), CPI for Rural Labourer (RL) and CPI (Rural/Urban/ Combined). The base year for CPI is 2012. The “Ministry of Labour and Employment” released the new series of Consumer Price Index for Industrial Worker (CPI-IW) with the base year as 2016. The Monetary Policy Committee (MPC) uses CPI data to control inflation. In April 2014, the Reserve Bank of India (RBI) adopted the CPI as its key measure of inflation.
Short Answer Questions
Write the answers briefly for the following questions.
Question 1.
Briefly explain the primary and secondary functions of Money.
Answer:
I. Primary Functions : The primary functions of money are both technical and essential to the functions of the economy. They are of two types :
a) Medium of exchange : Money serves as a medium of exchange. It removes the inconveniences of the barter system. Money facilitates the exchange of commodities without the need for a double coincidence of wants. Any commodity can be exchanged for money, enabling people to trade goods and services efficiently.
b) Measure of value (Unit of Account) : Money serves as a measure of the value of goods and services. As a common measure of value, it removes the difficulty of the barter system and simplifies transactions. The value of each commodity is expressed in units of money. Eg.: Indian Rupees, US Dollar.
II. Secondary Functions
Money has the following secondary functions:
a) Store of value : The value of commodities and services can be stored in the form of money. Certain commodities are perishable. If they are exchanged for money before they perish, their value can be preserved in the form of money. Otherwise, they perish and their value is lost forever. Even in the case of durable commodities, their value may diminish over a period of time. But their value can be stored, without any decline, in the form of money by exchanging them for money.
b) Standard of deferred payments : Money serves as a standard of deferred payments. In modem economies, most of the business transactions take place in the form of credit. An individual consumer or a business person may now purchase a commodity and pay for it in future, as this makes it possible to express future payments in terms of money. Similarly, one can borrow a certain amount of money now and repay it in future.
Question 2.
What are the monetary aggregates in India?
Answer:
Monetary aggregates (Measurement of Money Supply) : Following the recommendations of the Second Working Group on Money Supply (SWG), from April, 1997 the RBI has been publishing data on four alternative measures of money supply.
The respective empirical definitions of these measures are as follows;
M1 = Currency notes and coins with the public + demand deposits of the banks (current and savings deposits accounts) + other deposits of the RBI
M2 = M1 + Savings deposits with post office savings banks.
M3 = M1 + Net time deposits with the banking system.
M4 = M3 + Total deposits with the post office savings organisation (excluding National “Savings Certificate)
Note: Mi is known as “narrow money-and MS is known as “broad money”.
These measures are in decreasing order of liquidity. M1 is most liquid and easiest for transactions, whereas, M4 is least the liquid of all. Ms is the most commonly used measure of money supply. It is also known as the “aggregate monetary resource”.
Question 3.
Differentiate between Repo Rate and Reverse Repo Rate and their uses.
Answer:
Differentiate between Repo Rate and Reverse Repo Rate :
| Aspect | Repo Rate | Reverse Repo Rate |
| Definition | Interest rate at which the central bank lends money to commercial banks against securities. | Interest rate at which the central bank borrows money from commercial banks by selling securities. |
| Direction of Transaction
Purpose |
Central bank → commercial banks.
To provide short-term liquidity to banks. |
Commercial banks → Central Bank.
To absorb excess liquidity from banks. |
| Impact on Economy | Higher Repo rate increases borrowing cost for banks, reducing money supply and controlling inflation. | Higher reverse repo rate encourages banks to park funds with the central bank, reducing liquidity and controlling inflation. |
| Collateral | Banks provide government securities to RBI. | RBI provides securities to banks. |
| Use in Monetary policy | Controls inflation and stimulates or slows economic growth by influencing borrowing costs. | Regulate liquidity and stabilizes prices by managing excess funds in the banking system. |
| Typical Rate Relation | Usually higher than reverse repo rate. | Usually lower than repo rate. |
Uses : Repo Rate is used by the central bank to lend money to commercial bank to meet short term fund shortages and manage liquidity. By adjusting the repo rate, the central bank controls inflation and influences economic growth. A higher repo rate makes borrowing costly, reducing spending and inflation, a lower repo rate encourages borrowing and economic activity.
Reserve Repo Rate is used by the central bank to borrow money from commercial banks to absorb excess liquidity in the system, thus controlling inflation and maintaining Financial stability. Where the reserve repo rate is high, banks proper to keep surplus funds with one central bank, reducing money supply. A lower reserve repo rate encourages banks to lend more.
Question 4.
What are the quantitative credit controlling tools used by the RBI?
Answer:
Quantitative (or) General Measures :
a) Bank Rate The Bank Rate is the rate at which the Central Bank discounts the bills of commercial banks. It is also known as discount rate. If the Central Bank wishes to control credit and inflation in the economy, it raises the Bank Rate. If the Central Bank wishes to boost production and investment activities in the economy, it will decrease the Bank Rate.
b) Open Market Operations : It implies the deliberate direct sales and purchases of securities and bills in the market by the Central Bank on its own initiative to control the volume of credit. If RBI wants to discourage credit in the economy, it sell its securities. This step leads to contraction of credit and money in circulation.
c) Cash Reserve Ratio (CRR): CRR refers to that portion of total deposits which a commercial bank has to keep with the Central Bank in the form of cash reserves. Cash reserves determine the capacity of the commercial banks to create credit. During inflation the CRR is raised consequently, credit contracts. During deflation or recession, CRR is reduced. This will facilitate credit expansion.
d) Statutory Liquidity Ratio (SLR) : SLR refers to that portion of total deposits which a commercial bank has to keep with itself in the form of liquid assets like cash, gold or approved government securities. Liquidity impacts the credit creating ability of commercial banks.
If RBI wants to discourage credit in the economy, it increases SLR and if it wants to encourage credit in the economy, it decreases SLR.
e) Repo Rate : Repurchase options or in short ‘Repo’is defined as ‘an instrument for borrowing funds by selling securities with an agreement to repurchase the securities on a mutually agreed future date at agreed price, which includes interest for the funds borrowed. The interest rate charged by RBI for this transaction is called the “repo rate’. Changes in repo rate influence the quantity of credit in the economy.
f) Reverse Repo Rate : ‘Reverse Repo’ is defined as “an instrument for lending funds by purchasing securities with an agreement to resell the securities on a mutually agreed future date at an agreed price which includes interest for the funds lent”. The interest rate paid by RBI for such transactions is called the reverse repo rate. Changes in reverse repo rate lead to expansion or contraction of credit.
Question 5.
Define Inflation, state the types of Inflation.
Answer:
Definition : In a broader sense, the term inflation refers to a persistent rise in the general price level over a long period of time. Many modem economists agree that Inflation is a situation in which there is a persistent and appreciable increase in the general level of prices. Some of the important definitions are given below:
- According to Pigou, ‘inflation exists when money income is expanding more than in proportion to increase in earning activity’.
- Crowther defined inflation as ‘a state in which the value of money is falling, i.e, the prices are rising’.
- According to Ackley, ‘Inflation is a persistent and appreciable rise in the level or average of prices’.
- According to Samuelson, ‘Inflation denotes a rise in the general level of prices’
All definitions/agree that inflation refers to a rise in the general price level and that the rise is persistent.
Types : Inflation refers to a persistent rise in the general price level of goods and services over time. Inflation is divided into different types based on its pace or rate of inflation and the causes of inflation. They are explained below:
I. Based on the rate of inflation
- Creeping inflation : When the rise in the prices is very slow and small, it is called creeping inflation. Creeping inflation is also known as ‘mild inflation’. Under this, a gradual rise in prices is usually less than 3 per cent per annum. Creeping inflation is generally good for economic growth.
- Walking inflation : This is also referred to as ‘trotting inflation’. In this case, the inflation rate ranges between 3% and 5% annually.
- Running inflation : When the rate of inflation is in the range of 5% to 10% per annum, it is known as running inflation.
- Galloping (or) Hyper inflation : When the inflation rate exceeds 10 per cent annually, it is known as galloping inflation or hyper inflation.
II. On the basis of the cause
- Demand-Pull inflation : Inflation caused by an increase in the aggregate demand for commodities over aggregate supply is referred to as ‘demand- pull inflation’.
- Cost-push inflation : Prices of the commodities may rise due to a rise in the cost of production. Inflation caused by the rise in cost of production is called ‘cost-push inflation’,
Question 6.
Enumerate any eight factors of Demand and Supply that cause inflation.
Answer:
Inflation is generally caused by either excess demand or supply shortages, or increased production costs.
1. Factors causing increase in demand for commodities.
a) High rate of population growth.
b) Increase in non-plan and plan expenditure of the government.
c) Rise in the per capita income of the people due to economic development.
d) Increased spending by the government on employment programmes and welfare schemes.
e) Liberal availability of credit for unproductive economic activities.
f) Deficit financing by the Government.
2. Factors causing inadequate supply.
a) Failure of monsoons, floods, pests, use of spurious seeds etc. in agriculture.
b) Shortage of investment due to inadequate availability of institutional credit.
c) Non-availability (or) inadequate availability of inputs and raw materials.
d) Under-utilisation of productive capacity due to power shortage, labour unrest, etc.
e) Artificial scarcity due to black marketing.
Question 7.
Explain the components of demand for and supply of money.
Answer:
a) Demand for Money : The demand for money reflects why people desire a certain amount of money. Since money is needed for transactions, the value of transactions will determine the amount of money required. The greater the volume of transactions, the greater the demand for money. As volume of transactions depends on income, an increase in income will lead to a rise in demand for money.
When people keep their savings in the form of money rather than putting it in a bank, demand for money is high. How much money people keep also depends on rate of interest offered by banks. Specifically, when interest rates go up, people become less interested in holding money. Since holding money amounts to holding less of interest-earning deposits, and thus less interest received. Therefore, at higher interest rates, money demanded comes down.
b) Supply of Money : Money supply refers to the total amount of money circulating in an economy. The components of money supply may vary from country to country. Broadly speaking, money supply consists of the following:
- Currency issued by the central bank : In any country, the central bank issues currency, which includes paper notes and coins. In India, Reserve Bank of India, which is the central bank of the country, issues notes in the denominations of Rs. 500, 200, 100, 50, 20, 10, 5 and 2.
- Demand deposits created by commercial banks : Bank deposits are a prominent component of money supply. Commercial banks create credit from Third primary deposits of money receive from the public. The credit is created in the form of deposits known as derived or secondary deposits.
Question 8.
Define demonetisation and explain its advantages and disadvantages.
Answer:
Meaning : Demonetisation is an economic process where the existing currency unit (such as bank notes and coins) is withdrawn from circulation and replaced with new currency.
Demonetisation was an initiative taken by the Government of India in November, 2016 to tackle the problem of corruption, black money, terrorism and circulation of fake currency in the economy. Old currency notes of Rs.’500 and Rs. 1000 were declared no longer legal tender. New currency notes in the denomination of Rs. 500 and Rs. 2000 were launched. The public was advised to deposit old currency notes in their bank account till 31st December, 2016 without any declaration and upto 31st March, 2017 with the RBI declaration.
Advantages of Demonetisation
- Helps to minimise tax evasion and eliminate black money.
- Encourages a cashless society (digital payments network).
- Decreases a variety of criminal activities.
- Leads to an improvement in cash deposits.
Disadvantages of Demonetisation
- Damage to economic sentiment.
- Fall in employment in the unorganised sector.
- Slow growth rate of GDP.
- Public panic during the demonetisation process.
Question 9.
WPI and CPI. (Or)
Explain Methods of measuring inflation in India.
Answer:
Whole Sale Price Index (WPI) and Consumer Price Index (CPI) are two commonly used measures that later effective in determining the inflation in the country. WPI only consider changes in the price of goods. Whereas CPI considers changes in the prices of both goods and services.
a) Wholesale Price Index (WPI) : It measures the changes in the prices of goods sold and traded in bulk by wholesale businesses to other businesses. WPI indices are published by the Office of “Economic Adviser, Ministry of Commerce and Industry”. It is the most widely used inflation indicator in India. The base year for the all India WPI has been revised from 2004-05 to 2011-12 in 2017. The WPI was calculated using about 435 elements in the base year 1993-94, but 697 items in the advanced foundation base year 2011-12.
b) Consumer Price Index (CPI): It measures price changes from the perspective of retail buyers (consumers). It is released by the “National Statistical Office (NSO)” of the Ministry of Statistics and Program Implementation (MoSPI). The CPI calculates the difference in the price of commodities and services such as food, medical care, education, electronics etc, which Indian consumers buy for final consumption.
There are 4 types of CPI indices. They are CPI for Industrial Workers (IW), CPI for Agricultural Labourer (AL), CPI for Rural Labourer (RL) and CPI (Rural/ Urban/Combined). The base year for CPI is 2012. The “Ministry of Labour and Employment” released the new series of Consumer Price Index for Industrial Worker (CPI-IW) with the base year as 2016. The Monetary Policy Committee (MPC) uses CPI data to control inflation. In April 2014, the Reserve Bank of India (RBI) adopted the CPI as its key measure of inflation.
Very Short Answer Questions
Question 1.
Barter System.
Answer:
The Barter System is the oldest form of commerce where goods or services are exchanged directly without using money or any medium of exchange. In this system, two or more parties trade items or services. They have for those they need, based on mutually agreed values. For example, a carpenter might build a fence for a farmer who pays with crops instead of cash.
Question 2.
Liquidity.
Answer:
Liquidity can be defined as the ability of any asset to act as a direct medium of exchange. Money is the most liquid asset. The degree of liquidity differs from one asset to other asset.
Question 3.
Legal Tender Money.
Answer:
Legal Tender Money is the official currency recognised by law that must be accepted as payment for debts and financial obligations within a country. It typically includes coins and bank notes issued by the Government or Central Bank. In India, coins and currency notes issued by the RBI are legal tender.
Question 4.
Near Money.
Answer:
The term near money refers to those highly liquid asset which are not accepted as money i.e., they are not accepted but be easily converted into money within a short period.
Question 5.
Money Multiplier.
Answer:
The money multiplier (m) is defined as “the ratio of the change in the money supply to a given change in the monetary base (MJ”. It indicates how much the money supply will increase of a in high-powered money.
Money Multiplier (m) = \(\frac{\text { Money Supply }}{\text { Monetary Base }\left(\mathrm{M}_0\right)}\)
Thus, money multiplier indicates what multiple of the monetary base is transformed into money supply.
Question 6.
RBI.
Answer:
RBI is the Central Bank of India. It is established in April 1935 with a share capital of Rs.5 crores, as a shareholders bank. It was nationalized in 1949. It performs all the important functions of Central Bank under the Reserve Bank of India Act, 1934.
Question 7.
Bank Rate.
Answer:
The Bank Rate is the rate at which the Central Bank discounts the bills of commercial banks. It is also known as discount rate. If the Central Bank wishes to control credit and inflation in the economy, it raises the Bank Rate. If the Central Bank wishes to boost production and investment activities in the economy, it will decrease the Bank Rate.
Question 8.
RTGS.
Answer:
The RTGS system is a funds transfer mechanism where the transfer of money takes place from one bank to another on a ‘real time’ and on ‘gross basis’. This is the fastest possible money transfer system through the banking channel. Settlement in real time means payment transaction is not subjected to any waiting period. The transactions are settled as soon as they are processed. In India, the Reserve Bank of India maintains this payment network. There is no limit on the amount to be transferred.
Question 9.
Cash Reserve Ratio.
Answer:
CRR refers to that portion of total deposits which a commercial bank has to keep with the Central Bank in the form of cash reserves. Cash reserves determine the capacity of the commercial banks to create credit. During inflation the CRR is raised consequently, credit contracts. During deflation or recession, CRR is reduced. This will facilitate credit expansion.
Question 10.
Open Market Operation.
Answer:
It implies the deliberate direct sales and purchases of securities and bills in the market by the Central Bank on its own initiative to control the volume of credit. If RBI wants to discourage credit in the economy, it sell its securities. This step leads to contraction of credit and money in circulation.
Question 11.
Lender of Lost Resort.
Answer:
In times of financial stringency, the scheduled banks can approach the RBI as a last resort. The RBI grants loans against the securities such as the treasury bonds, treasury bills, etc. This, acts as the lender of last resort.
Question 12.
High Powered Money.
Answer:
It is also called the monetary base, is the total amount of currency in circulation plus the reserves the commercial banks hold at the central bank. It includes physical currency and bank reserves deposited with the central bank.
This money is termed high-powered because a small change in it can lead to a much larger change in the overall money supply through the money multiplier effect in the fractional reserve banking system. Central Banks control high powered money directly and use it as a key tool to implement monetary policy influencing interest rates, inflation, and economic stability.
Question 13.
Consumer Price Index.
Answer:
CPI is one of the price indices to know about inflation. This is the index of prices of a given basket of commodities which are brought by the representative consumer. It is generally expressed in percentage terms. Here we calculate the cost of purchase of a given basket of commodities for both base year and current year.
Question 14.
Stagflation.
Answer:
The term “Stagflation” is a combination of the words ‘stagnation’ and ‘inflation’. Stagflation refers to an economic condition characterised by high inflation, low economic growth and high unemployment.
One Word Answer Questions
Answer the following questions in ONE WORD.
Question 1.
What is the full form of the IFSC?
Answer:
Indian Financial System Code
Question 2.
The latest ‘Demonetisation measure’ was taken by Govt, of India on.
Answer:
November 2016
Question 3.
MI + Net time deposits with the banking system is equal to :
Answer:
M3
Question 4.
The ratio of change in the money supply to a given change in the monetary base is known as :
Answer:
Money Multiplier
Question 5.
“An instrument for borrowing funds by selling securities with an agreement to repurchase on a mutually agreed future date” is called: ___________
Answer:
Repo Rate
Fill in the blanks
Question 1.
___________ measure of money supply is known as broad money.
Answer:
M3
Question 2.
“Money is what money does”. This definition of money is given by ___________.
Answer:
Walker
Question 3.
Currency in circulation + Banker’s deposits with the RBI + Other deposits with the RBI is equal to ___________.
Answer:
Reserve Money (M0)
Question 4.
During inflation, the purchasing power of money ___________.
Answer:
Decreases
Question 5.
___________ is responsible for overall credit and monetary policy in India.
Answer:
RBI
Multiple Choice Questions
Question 1.
Which of the following is not a quantitative credit controlling measure by
the RBI?
1) Repo Rate
2) Bank Rate
3) CRR
4) Margin Requirements
Answer:
4) Margin Requirements
Question 2.
Which of the following currency notes were demonetised in 2016?
1) Rs. 100 & 200
2) Rs.200 & 500
3) Rs. 500 & 1000
4) Rs.500 & 200
Answer:
3) Rs. 500 & 1000
Question 3.
The rate at which Rupee was borrowed by commercial banks from the RBI is known as:
1) SLR
2) Repo Rate
3) Reverse Repo Rate
4) CRR
Answer:
2) Repo Rate
Question 4.
When the aggregate demand exceeds aggregate supply, it results in:
1) Demand-pull Inflation
2) Cost-push Inflation
3) Hyper Inflation
4) Creeping Inflation
Answer:
1) Demand-pull Inflation
Question 5.
Which of the following statement is true?
1) M3 is the most liquid money supply measure
2) M2 is the most liquid money supply measure
3) M1 is the most liquid money supply measure
4) M4 is the most liquid money supply measure
Answer:
3) M1 is the most liquid money supply measure